🇺🇸 A trusted non-government website. Here's how you know
Call Us To Get Free, Local Help With Your Medicare Planning Process:
Buffalo, NY's Top Medicare Planning Service
Serving Akron, Alden, Amherst, Cheektowaga, Clarence, Depew, Lancaster, Williamsville And All Surrounding Areas Of Erie County

"Can I Wait To Sign Up For Medicare If I Will Keep Working?"
By Andrew Hibbard
YES! A Real, Happy And Helpful Human Wrote This (No AI Software Was Used)
Updated On: July 25, 2026
TIME TO READ: 3 MINUTES
By Andrew Hibbard
YES! A Real, Happy And Helpful Human Wrote This (No AI Software Was Used)
Updated On: July 25, 2026
TIME TO READ: 3 MINUTES
YOUR SUMMARY OF KEY TAKEAWAYS
- If you’ll keep working past age 65 and your Employer has 20 or more employees, you may not need to sign up for Medicare as long as your healthcare is considered “creditable coverage” based on the new rule changes passed by Congress.
- If you’ll keep working past age 65 and your Employer is 19 or less employees, you are self-employed, or your current healthcare coverage is not offered to every employee equally, you likely will need to sign up for Medicare (both Part A&B), to protect yourself from paying a permanent late penalty.
- If either you, or both you and your Employer, are contributing to an H.S.A. on your behalf, you have different rules and requirements regarding IRS tax surcharge fines and whether you must sign up for Medicare while working, or if you can wait without a getting into big trouble.
If you, or your spouse, will continue to work past the age of 65, you may be allowed to wait with signing up for Medicare.
Now, this doesn’t mean you shouldn’t wonder if you should still do something or worry about paying a permanent late penalty.
You aren’t entirely off the hook, and quite frankly, when delaying your Medicare benefits, you will have more complications and coordination than those who will sign up for Medicare at age 65.
To help you make a better, more informed decision, here are a few qualifying questions to ask yourself…
QUESTION #1: Do you, or your spouse, work for an employer with 20 or more active employees, who is proving you (and/or your spouse) health insurance benefits from that job?
ANSWER: Contrary to popular belief, not everybody needs to sign up for Medicare at age 65. Many have heard the myth that “You Have To Sign Up For Medicare Or You’ll Get A Late Penalty.” That’s not true.
You may be able to do nothing with Medicare, and wait to sign up for both your Medicare Part A&B benefits until after age 65 (when you stop working and your Employer Group Health Plan ends) without paying a late enrollment penalty.
You may also only be allowed to suspend your Part B benefit, but must sign up for your Part A, if your Employer requires it.
All I am saying is you will need to confirm your current health insurance from your employer meets the new, confusing rule changes and requirements regarding “credible coverage” passed by Congress recently.
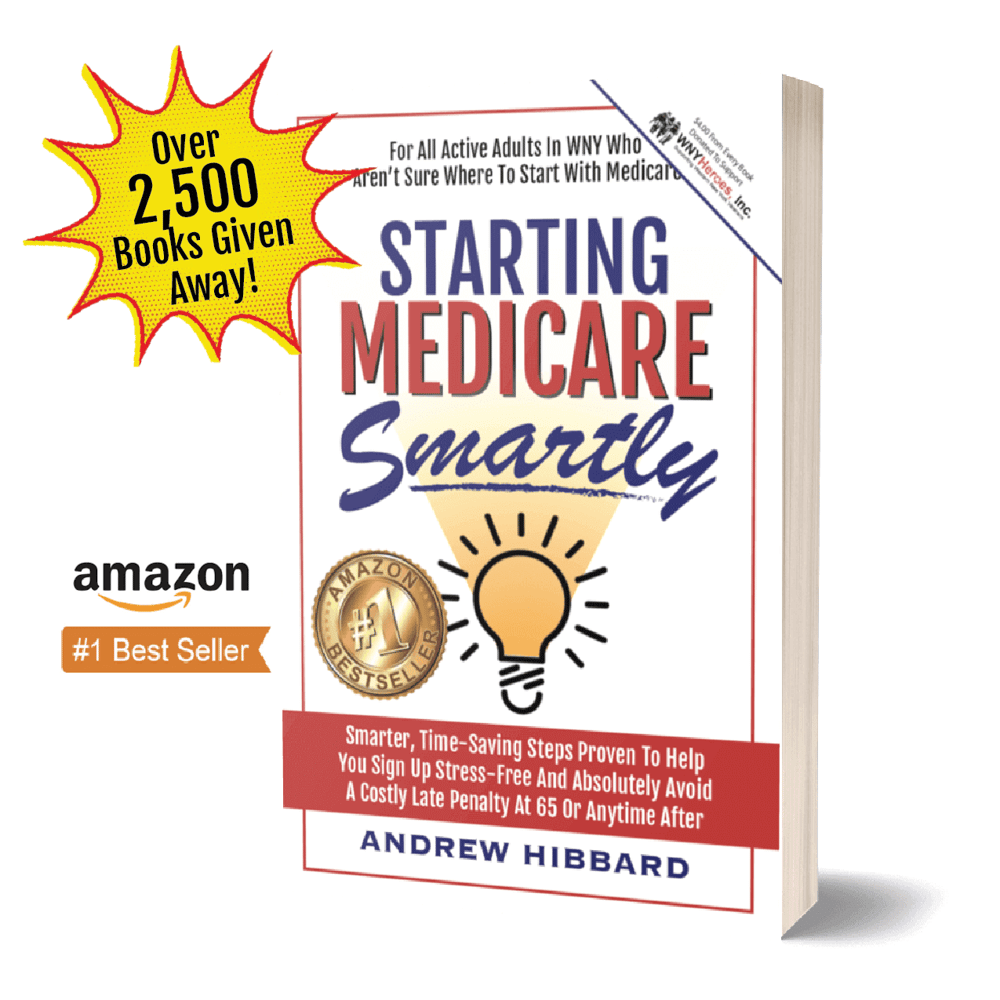
I always suggest to anyone who reads my articles, or gets a free copy of my #1 best-selling book, Starting Medicare Smartly, or who comes into my office in Clarence where I manage the free, nationally-recognized and 5-star rated, Medicare SmartStart Program™️ to be proactive and pre-file what’s called a “Preliminary Proof Of Credible Coverage” form.
This is super smart and easy for me to do FOR YOU, where we can start a paper trail record to make your application process in the future much smoother and more seamless. Feel free to give me a call at (716) 833-0252 and we can sit down, I can give you my second set of eyes on your situation, so you know no assumptions are being made and have complete peace-of-mind to all but guarantee you will not pay a permanent penalty later in life.
**DISCLAIMER** If you have a high-deductible healthcare plans at work, with a Health Savings Account (H.S.A.) either you, and/or your Employer, are contributing to, there are different rules and requirements you must follow to prevent big problems where you’ll have to withdraw and pay back any H.S.A. contributions you made, lose the write-off deduction, and be forced to pay a costly IRS surcharge fine when you file your taxes. This is a place you do NOT want to be and can be absolutely avoided with proper planning.
QUESTION #2: Do you, or your spouse, work for an employer with 19 or less active employees, who is providing you (and/or your spouse) health insurance benefits from that job?
ANSWER: Unlike working for an Employer with 20 or more active employees, if you, or your spouse, work somewhere with 19 or less active employees, you likely will be required to sign up and start both Medicare Part A and Part B even if you choose to keep working, otherwise your Employer Group Healthcare Plan (EGHP) may not cover the costs for and medical services you need, or receive, because you are eligible for Medicare at 65, but you did not enroll.
In this instance, when you sign up for Medicare Part A&B benefits, your Medicare coverage would be considered your primary payer while your healthcare coverage from your job would pay secondary.
Also, in most cases, when working at a small-group Employer with 19 or less employees, if you wait to sign up for your Medicare Part A&B benefits past age 65, you can be certain you will pay a permanent late enrollment penalty for life.
QUESTION #3: Will you, or your spouse, keep working past age 65, and are self-employed, or have health insurance that is not available to everyone equally at your employer?
ANSWER: You will need to ask, (and I strongly suggest requesting written verification), if your health insurance is considered “creditable coverage” deemed acceptable by the new rule changes. If it is not creditable, you will be required to sign up and start both Medicare Part A&B at 65 regardless of your alternative healthcare options, otherwise you will be assessed a permanent late enrollment penalty for life.
And honestly, if you are in the situation and you even have to ask, or question what you should or shouldn’t be doing, it’s likely smarter…and safer…to speak with an expert to be confident and certain what you need to be done, when, and why.
There’s no good reason why you would want to roll the dice on bad advice from your HR Rep, or what your friend or family member, might tell you to do. They likely have no clue about all these new rule changes, and listening to them without confirming for yourself, you will be at serious risk of missing something and making a costly mistake.
** NOTE** The good news is, you don’t have to do anything with Medicare on your own. As the one and ONLY approved Certified Starting Medicare Specialist™️ for Erie County, my office does offer the benefit of Medicare SmartApp application services on-site where we are authorized to, not only complete and submit your Federal Medicare applications FOR YOU --- FREE, but we also have the ability to speed up the time it takes for approval, shortcutting the typical 2-3 months down to 2-3 weeks, sometimes as fast as 2-3 days. Let me take away the stress of you trying to tackle anything with Medicare on you own! We are always happy to help in any way we can, you just have to ask…
Due to our reputation and popularity being voted #1 best Medicare planning service in the area for the last 6 years in a row, appointments are limited and fill up fast. To see if you qualify to use the free, nationally-recognized and 5-star rated, Medicare SmartStart Program™️ I manage, call my local office in Clarence right now at (716) 833-0252. (Really the only people I can't help and the ones who never call).
What Can We Help You With Next ?
What Can We Help You With Next ?
*** MOST POPULAR ***
FREE LOCAL IN-PERSON HELP
Rely On A Certified Starting
Medicare Specialist™ And Enjoy
Personalized Medicare Planning
Done-For-You...Absolutely FREE!
FREE #1 BEST-SELLING BOOK
Learn Smarter, Time-Saving
Steps Proven To Help You
Sign Up For Medicare Stress-Free
At Age 65...Or Anytime After
BACK TO FREE ARTICLE ARCHIVE
Get More Accurate Answers
And Advice From Buffalo's #1
Top Medicare Planning Expert
Andrew Hibbard

You Can Feel Confident Knowing What To Do With Medicare.
I Can Take Away The Stress Of Trying To Tackle It On Your Own.
Figuring out all the fine print with Medicare doesn't need to feel stressful. You don't have to spend your scarce free time at home, alone, in isolation, relying on your own assumptions and hit-or-miss guesses, attempting to do-it-yourself.
Confidently knowing exactly what to do with Medicare (and when) is THE KEY to prevent making any of the common mistakes and protect yourself from paying a late penalty for life...and only the FREE Medicare SmartStart Program™ will show you how!
If you don't have the time or the desire to deal with Medicare directly, and want a BETTER, SMARTER, time-saving solution to short-cut hours of your own trial and error so you know --- without question --- everything is done, done right, and done on time.
Let me put my proven 3-step Medicare SmartStart Program™ to work for you --- for FREE --- and get everything expertly done-for-you without you really having to do much of anything other than ask...
Click the BIG [YES! I Want Your Free Help, Andrew!] BUTTON below to take the next step and schedule a complimentary Medicare SmartStart Strategy Session with me --- it's that easy!

Who Is Andrew Hibbard?
Since 2015, Andrew has helped over 2,100+ WNY'ers through the free, 5-star rated and nationally recognized Medicare SmartStart Program™ to take away all the stress folks suffer with trying to tackle Medicare on their own. His impressive record of success has Andrew featured in Forever Young Magazine and the BEE Group Newspapers, exclusive interviews on WECK Radio's Senior Matter's Program, nominated to Buffalo Business First 40 Under 40 (2023), and listed in Marque's Who's Who In America (2024). He is the author of the award-winning #1 best-selling book, "Starting Medicare Smartly," which reveals the new, confusing rule changes for signing up for Medicare the first time and how to avoid common mistakes, not mess anything up, and prevent paying a permanent late penalty at 65 or anytime after